SOLA Wind, Hail & Tornado Deductible Protection
Protect Yourself From Large Storm Deductibles
Many homeowners today are discovering that their insurance policy includes a wind, hail, or tornado deductible that can be thousands of dollars higher than their standard deductible. In some cases, these deductibles are based on a percentage of your home’s insured value, creating significant out-of-pocket costs after a severe storm.
SOLA provides an innovative deductible protection solution designed to help homeowners manage these unexpected expenses. Rather than replacing your homeowners insurance policy, SOLA works alongside it to provide financial assistance when qualifying wind, hail, or tornado events impact your property.
At ALINK Insurance Services®, we help homeowners evaluate whether SOLA may be a valuable addition to their overall protection strategy.
How SOLA Works
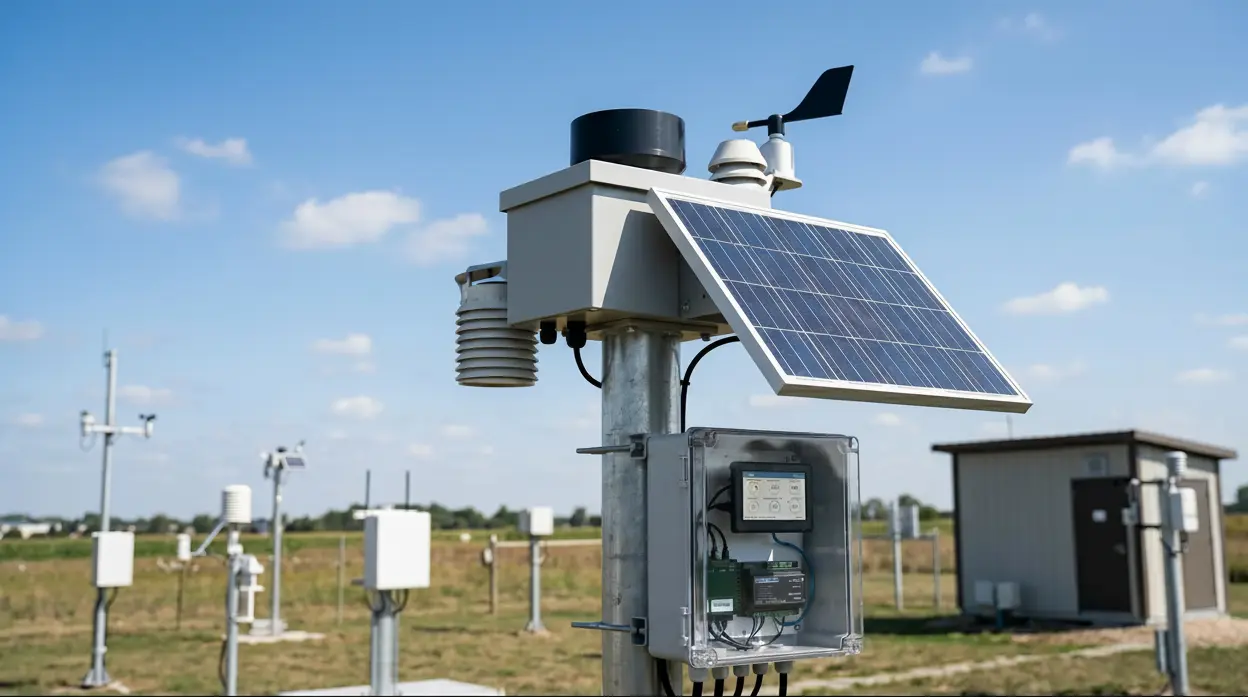
SOLA uses advanced weather monitoring technology to track wind, hail, and tornado activity across covered areas. When a qualifying weather event occurs:
- SOLA verifies that your property was impacted by a qualifying storm event.
- Property damage is confirmed through submitted photos or documentation.
- If the event meets SOLA’s coverage criteria, a payment may be issued directly to you.
- Funds can be used toward your homeowners insurance deductible or other eligible out-of-pocket storm-related expenses.
Unlike traditional insurance claims, SOLA utilizes verified weather data and a streamlined review process designed to provide a faster and more predictable experience. Coverage terms, conditions, and payment amounts vary by policy and state.¹
Why Homeowners Are Considering SOLA
As insurance companies continue increasing wind and hail deductibles in many regions, homeowners are looking for ways to reduce their financial exposure after a major storm.
Potential benefits may include:
Help With High Percentage Deductibles
Many homeowners policies now include separate wind or hail deductibles that can range from 1% to 5% of the home’s insured value. SOLA can help offset these potentially significant expenses when qualifying events occur.²
| Home Insured Value | 1% Deductible | 2% Deductible | 5% Deductible |
| $500,000 | $5,000 | $10,000 | $25,000 |
| $750,000 | $7,500 | $15,000 | $37,500 |
| $1,000,000 | $10,000 | $20,000 | $50,000 |
Fast Claims Experience
SOLA relies on verified weather data and a simplified claims process that may allow eligible payments to be issued more quickly than traditional property claims.³
Coverage Designed For Severe Weather Risks
Coverage is specifically designed around common storm-related threats including:
- Hail
- Straight-line winds
- Tornadoes
Protect Your Financial Stability
Unexpected storm deductibles can place strain on household budgets. SOLA helps provide an additional layer of financial protection when severe weather strikes.
Who May Benefit From SOLA?
SOLA may be worth considering if you:
- Have a wind or hail deductible that is higher than you are comfortable paying out of pocket.
- Live in an area prone to hailstorms, tornadoes, or severe wind events.
- Recently increased your deductible to lower your homeowners insurance premium.
- Want additional protection against large storm-related expenses.
- Are concerned about rising homeowners insurance costs and deductibles.
Frequently Asked Questions
No. SOLA is designed to complement your homeowners insurance by helping address qualifying wind, hail, and tornado deductible expenses. It does not replace your underlying homeowners coverage.
SOLA provides coverage based on policy terms and qualifying weather events. Payment amounts depend on the coverage selected and the nature of the event.
Yes. SOLA is intended to work alongside an existing homeowners insurance policy.
Coverage is generally designed for qualifying wind, hail, and tornado events, subject to policy terms and state availability.
Availability varies by state and underwriting guidelines.
Learn More About SOLA Coverage
If your homeowners policy includes a significant wind, hail, or tornado deductible, SOLA may help provide additional financial protection when severe weather occurs.
Our team can review your current homeowners policy, explain how percentage deductibles work, and help determine whether SOLA coverage may be appropriate for your situation.
Contact ALINK Insurance Services® today for a personalized review and quote.
¹ Coverage subject to policy terms, conditions, exclusions, and state availability.
² Percentage deductibles vary by insurance carrier and policy.
³ Payment timing depends on event verification, claims documentation, and policy provisions.